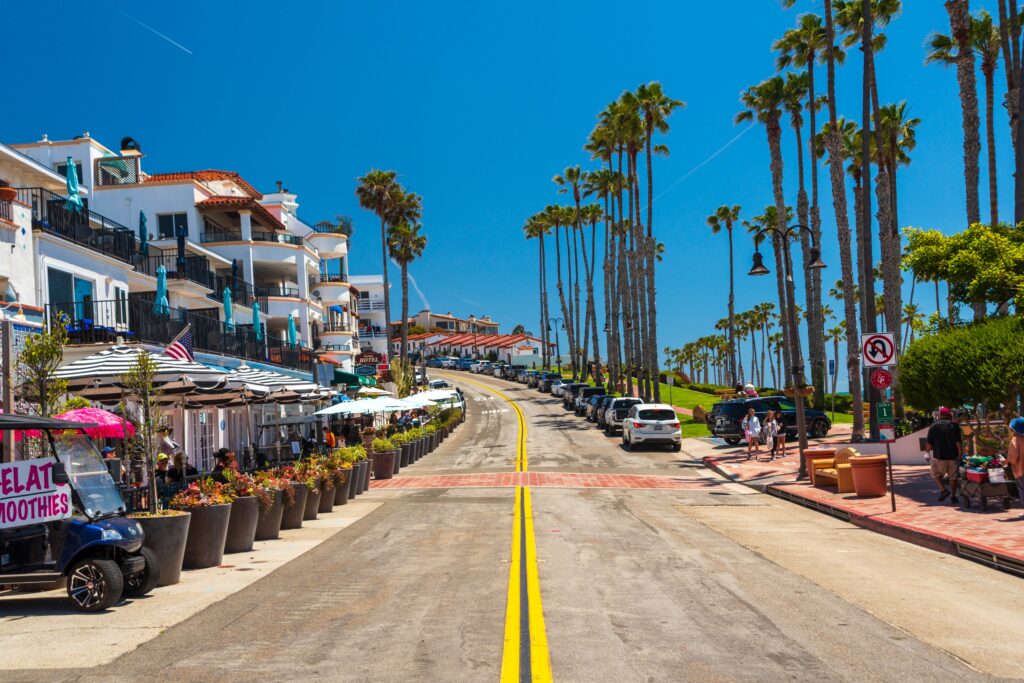
Golf carts and low-speed electric vehicles have become a familiar sight in and around San Clemente and Dana Point — running errands, heading to the beach, cruising around planned communities and gated neighborhoods. They feel casual and low-stakes compared to a car, which is exactly why so many owners are surprised to learn how much legal complexity actually surrounds them. California draws sharp, specific lines between a “golf cart,” a “low-speed vehicle” (LSV), and a “neighborhood electric vehicle” (NEV) — and which category your vehicle falls into determines everything from whether you need a license and insurance to whether you’re covered at all if something goes wrong.
Golf Cart, LSV, and NEV: Three Different Legal Categories
It’s worth clearing up a common point of confusion right away: “NEV” and “LSV” are the same legal classification under California Vehicle Code Section 385.5, just with different names used in different contexts — NEV shows up most often in HOA and community association documents, while LSV is the term the DMV and CHP use for registration and enforcement. Both refer to a four-wheeled electric vehicle capable of exceeding 20 mph but not more than 25 mph, built to federal safety standards (FMVSS 500), with a manufacturer-assigned 17-digit VIN.
A standard golf cart is legally distinct and far more limited. Under California Code of Regulations Title 13, Section 2411, a golf cart is defined specifically as a vehicle used to convey golf equipment and up to two people on a golf course — a narrow definition that doesn’t cover the kind of everyday neighborhood use most people actually have in mind. Critically, California doesn’t allow a standard golf cart to simply be modified — adding lights, mirrors, and seat belts — and then registered as an LSV. If a vehicle wasn’t manufactured to LSV specifications from the factory, with a proper VIN and FMVSS 500 certification, it doesn’t qualify for LSV registration regardless of what equipment gets added later.
This distinction matters enormously for liability purposes, because it determines what roads a vehicle can legally use and what insurance is actually required.
Where Each Category Can Legally Drive
A standard, non-upgraded golf cart has very limited street access — generally restricted to golf courses and any streets specifically authorized by local ordinance, such as certain gated community roads. A properly registered LSV/NEV, by contrast, can operate on any California public road with a posted speed limit of 35 mph or less, under Vehicle Code Section 21260 — which covers most residential streets and many connector roads throughout San Clemente and Dana Point’s beach neighborhoods.
This broader road access comes with broader legal obligations. Once an LSV is on a public road, Vehicle Code Section 21251 requires it to be registered with the DMV just like any other motor vehicle, and it becomes subject to essentially the full range of rules that apply to a standard car, with only limited exceptions tailored to its lower top speed.
Insurance: Where Owners Get Caught Off Guard
This is the area where we see the most confusion — and the most exposure — among golf cart and NEV owners. Under Senate Bill 1107, effective January 1, 2025, California requires registered LSVs to carry a minimum of $30,000 per person, $60,000 per accident in bodily injury liability coverage, and $15,000 in property damage coverage (commonly written as 30/60/15) — an increase from the previous, lower minimums.
The bigger issue isn’t the amount of required coverage; it’s the assumption that an existing policy already covers the vehicle. A homeowner’s insurance policy generally will not cover a golf cart or LSV involved in an accident on a public road, since these policies typically carry the same kind of motorized-vehicle exclusion discussed in our post on e-bike insurance gaps. Driving an unregistered or improperly insured cart on a public road doesn’t just risk a citation — if you cause an accident while driving one, your personal financial exposure can be significant, since neither your homeowner’s policy nor, in many cases, your auto policy will step in to cover it.
The safest approach for any golf cart or NEV owner in a beach community is to confirm the specific classification of the vehicle (golf cart, LSV, or NEV — remembering that NEV and LSV are the same thing under a different name), register it properly if it qualifies as an LSV, and carry a dedicated LSV liability policy rather than assuming existing coverage extends to it.
Golf Carts, Minors, and Negligent Entrustment
Beach communities throughout South Orange County have a well-established, if not always fully legal, tradition of teenagers driving golf carts and NEVs around gated neighborhoods, sometimes years before they’re old enough for a standard driver’s license. This is worth addressing directly, because it creates real legal exposure that many families don’t fully appreciate. A properly registered LSV/NEV operating on a public road requires the driver to hold a valid driver’s license, the same as any other motor vehicle — there is no special reduced-age exception for low-speed vehicles once they’re on a public street, regardless of how common underage driving of these vehicles may be within a given community. A parent who allows an unlicensed minor to drive a registered LSV on public roads, or who allows a minor to drive any cart — registered or not — in a way the parent knows or should know is unsafe, can face liability under a negligent entrustment theory similar to the one discussed in our post on e-bike accidents involving minors, separate from and in addition to the minor’s own potential responsibility for causing an accident. Even within a private, HOA-governed community where local rules might tolerate underage cart use on internal roads, that tolerance doesn’t extend to public streets, and it doesn’t eliminate a parent’s potential liability if an accident results in injury to someone else.
HOA Rules Are a Separate Layer, Not a Substitute for DMV Compliance
Many of San Clemente and Dana Point’s planned communities and gated neighborhoods have their own rules about golf cart and NEV use — designated routes, speed limits within the community, registration with the HOA itself, and so on. It’s important to understand that these are separate from, and don’t substitute for, DMV registration and insurance requirements. An HOA might permit golf cart use on its private roads under its own community rules, but the moment that same vehicle crosses onto a public street, the state’s registration, insurance, and vehicle classification requirements apply regardless of what the HOA’s internal rules say. We’ve seen cases where an owner reasonably assumed that because their HOA allowed cart use throughout the community, they were also covered to drive on the public streets connecting different sections of a larger development — an assumption that can leave a gap in both legal compliance and insurance coverage.
Common Accident Patterns
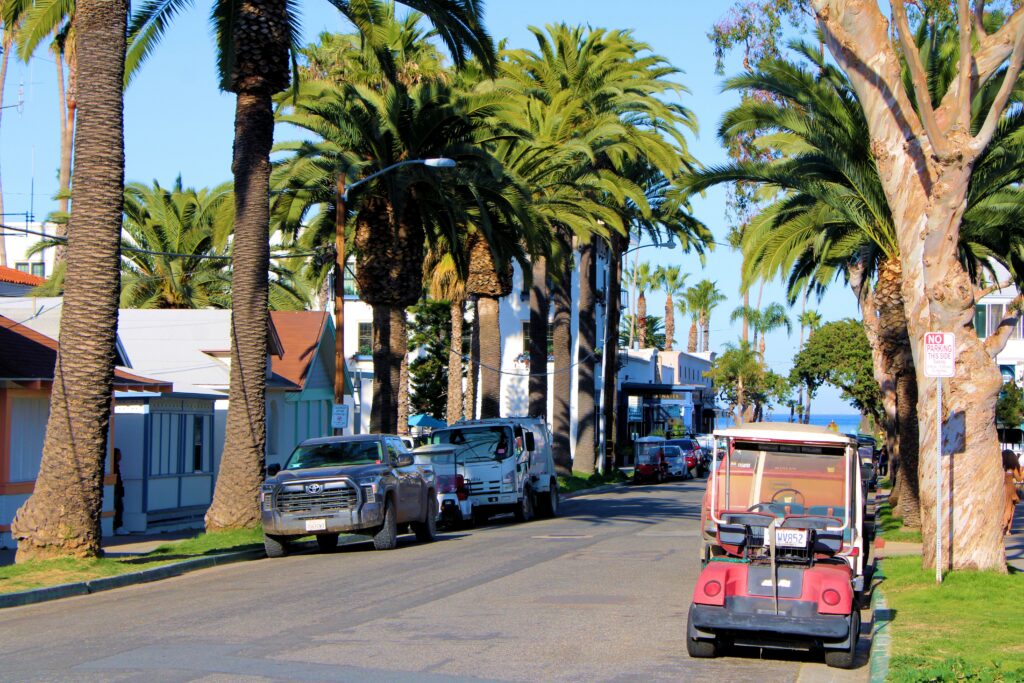
- Intersection collisions with cars. Golf carts and LSVs are considerably smaller, slower to accelerate, and lower to the ground than standard vehicles, which makes them harder for drivers to judge in terms of distance and closing speed — similar to the visibility challenges discussed in our post on left-turn accidents involving motorcyclists and cyclists. A driver misjudging how quickly a cart will clear an intersection is a recurring cause of these collisions.
- Rollover and loss-of-control accidents. Golf carts and LSVs have a comparatively high center of gravity and were never engineered with the same stability standards as a standard passenger vehicle. Sharp turns taken at speed, especially with multiple passengers, are a common cause of single-vehicle rollover accidents — and because most carts lack the safety cage, airbags, and crumple zones of a standard car, injuries in these accidents are often more serious than the low speeds involved might suggest.
- Passenger ejection. Many golf carts and NEVs, particularly older or non-upgraded models, lack seat belts or doors, and passengers — especially children — can be ejected during a sudden stop, sharp turn, or collision that a seat-belted occupant in a standard vehicle would walk away from largely unharmed.
- Nighttime visibility incidents. Golf carts and LSVs are far less visible than standard vehicles after dark, particularly older models without a full complement of headlights, taillights, and reflectors. Evening beach outings and community events are a common setting for these low-visibility collisions.
Who Can Be Held Liable
- The cart’s driver, for standard negligence — failing to yield, excessive speed for conditions, or a rollover caused by reckless turning.
- The vehicle’s owner, if the owner allowed an unlicensed or clearly unsafe driver to operate the cart, under a negligent entrustment theory similar to the one discussed in our e-bike post regarding minors and vehicle access.
- A manufacturer or seller, if a defect in the cart itself — a steering failure, a defective braking system, or a design flaw contributing to rollover risk — caused or worsened the accident, under California’s product liability framework.
- An HOA or community association, in more limited circumstances, if a dangerous condition on community property — poor lighting, an unmarked hazard, inadequate signage on a designated cart route — contributed to the accident, under a premises liability theory similar to the slip-and-fall framework discussed elsewhere on our blog.
What to Do If You’re Involved in a Golf Cart or NEV Accident
- Determine the vehicle’s actual classification early. Whether the cart involved was a standard golf cart, a properly registered LSV, or an unregistered vehicle being driven as if it were street-legal significantly affects both the insurance analysis and any potential citations involved.
- Check for seat belt use and ejection. Given how much more severe cart accident injuries can be without proper restraints, documenting whether the cart had seat belts and whether they were in use is an important early step.
- Ask whether the accident occurred on public or private/HOA property. This affects which rules applied at the time and, if a public entity’s infrastructure was somehow involved, whether the shortened government claims deadline discussed elsewhere on our blog might apply.
- Confirm what insurance, if any, covers the vehicle. Given how often golf cart and NEV owners are underinsured or entirely uninsured for their vehicle, this is one of the more important early questions in any claim.
Confirming Your Vehicle’s Status Before Something Goes Wrong
If you own or regularly use a golf cart, LSV, or NEV in a South Orange County beach community, the single most valuable thing you can do is confirm — in writing, from your insurer and, if applicable, the DMV — exactly how your specific vehicle is classified and what coverage actually applies to it. Given how often we see owners assume coverage exists where it doesn’t, this is a rare case where a proactive phone call before an accident can matter as much as anything done afterward.
A Casual Vehicle With Serious Legal Stakes
Golf carts and NEVs feel like a low-stakes way to get around a beach community, and most of the time, they are. But the legal and insurance framework around them is more specific — and less forgiving of assumptions — than most owners realize, and the physical vulnerability of these vehicles means accidents involving them can be more serious than their low top speed might suggest.
If you’ve been injured in a golf cart or NEV accident in San Clemente, Dana Point, or a surrounding beach community, Rosen Law Offices offers free consultations to help you understand your options. Call us at (949) 335-0020.
This article is intended for general informational purposes and does not constitute legal advice. Every accident involves unique facts, and the outcome of any claim depends on the specific circumstances involved. If you’ve been injured, consult with a licensed attorney about your particular situation.